
Showing posts with label realtor. Show all posts
Showing posts with label realtor. Show all posts
Monday, January 9, 2017

Monday, December 12, 2016

Monday, October 10, 2016

Monday, September 12, 2016

Monday, August 8, 2016

Monday, June 13, 2016

Wednesday, May 18, 2016
Coldwell Banker Real Estate Announces First-Of-Its-Kind Smart Home Education Curriculum Exclusively For The Coldwell Banker Network
Coldwell Banker Real Estate LLC, the original Silicon Valley real estate start-up founded in 1906, announced today the launch of a smart home education curriculum available exclusively for the Coldwell Banker® brand and its affiliated franchised brokers and agents. The curriculum, a real estate industry first, was created in partnership with CEDIA, the global trade association for the home technology market, and is available to all members of the Coldwell Banker network. It will be offered by a CEDIA instructor through Coldwell Banker University.
"Smart home technology is becoming a source of convenience, security and comfort in homes across the United States, with almost half of all Americans owning or planning to invest in smart home technology by the end of 2016, according to the Coldwell Banker Smart Home Marketplace Survey," said Budge Huskey, president and chief executive officer of Coldwell Banker Real Estate, LLC. "We believe it is our responsibility to ensure that our affiliated agents are the foremost experts in every aspect of the home. As ambassadors to the home, it is imperative for our affiliated agents to learn about smart home products and provide exceptional advice for homebuyers interested in smart home integration."
Developed by CEDIA, the Coldwell Banker curriculum will provide an extensive look into the evolution of home technology and recent rise of the smart home with a focus on how smart home products are changing the way we live in and interact with our homes. This program will equip attendees with the skills needed to advise buyers looking to invest in a smart home and sellers looking to stage and showcase their smart homes. Upon completion of the optional course, the participants will receive a certificate.
"CEDIA is at the forefront of home technology design and installation, so it made sense for us to join forces with the leading smart home real estate company to create this education curriculum," said Vin Bruno, CEDIA CEO. "This curriculum will give Coldwell Banker affiliated agents a tremendous advantage, providing them insight into the most up-to-date smart home developments and how technology can benefit their clients to live their best lives at home. Agents who complete this program will have a better ability to market listings more effectively and provide valuable information to the communities they serve."
About Coldwell Banker Real Estate LLC
Since 1906, the Coldwell Banker® organization has been a premier provider of full-service residential and commercial real estate brokerage services. Coldwell Banker Real Estate is the oldest national real estate brand and franchisor in the United States, and today has a global network of approximately 3,000 independently owned and operated franchised broker offices in 47 countries and territories with almost 85,000 affiliated sales professionals. The Coldwell Banker brand is known for creating innovative consumer services as recently seen by taking a leadership role in the smart home space, being the first national real estate brand with an iPad app, the first to augment its website www.coldwellbanker.com for smart phones, the first to create an iPhone application with international listings, the first to develop an iPad application (CBx) to easily bring big data into home listing presentations, and the first to fully harness the power of video in real estate listings, news and information through its Coldwell Banker On LocationSM YouTube channel. Coldwell Banker is a leader in niche markets such as resort, new homes and luxury properties through its Coldwell Banker Previews International® marketing program delivering exceptional experiences for all consumers served.
About CEDIA
CEDIA members deliver technology solutions that allow people to have their best moments in life from the comfort of their own home. Life lived best at home. CEDIA is the international trade association and central touch point for 3,700 member companies that represents every facet of the ever-evolving technology market. Follow @CEDIA on Twitter, find us on Facebook atwww.facebook.com/CEDIA.Region2, or join the CEDIA group on LinkedIn.
Monday, May 9, 2016

Monday, March 14, 2016

Saturday, February 20, 2016
Thursday, February 18, 2016

Wednesday, February 17, 2016
Coldwell Banker Real Estate and Adopt-a-Pet.com Launch Second Year of the Homes for Dogs Project
Dogs make every day awesome. This theme will continue as Coldwell Banker Real Estate LLC, the original Silicon Valley real estate startup founded in 1906, extends the successful "Homes for Dogs Project" into 2016, which last year found homes for more than 20,000 dogs. The continuation of the campaign will provide more opportunities for Coldwell Banker® affiliated offices to join forces with local shelters and rescue groups through their association with Adopt-a-Pet.com.
"There is no doubt that pets play a critical role in the emotional connection we have with the places we call home," said Sean Blankenship, chief marketing officer for Coldwell Banker Real Estate LLC. "Last year's 'Homes for Dogs' campaign was a truly integrated program, bringing together our national and local Coldwell Banker offices and more than 650 animal shelters nationwide. It was inspiring to see our brokers and agents come together with the shelter communities to find a home for home's best friend."
Driving over 8.5 million views online in 2015, the "Home's Best Friend" commercial was rated the highest performing advertisement in the real estate category by AceMetrix, a leader in advertising measurement and analytics. The Coldwell Banker brand will launch another canine-centric commercial as part of a new television and online video campaign being released in March. Both ads will close by driving awareness of the Homes for Dogs Project. The brands will also host another National Pet Adoption Weekend in the fall.
"We continue to be motivated by the commitment Coldwell Banker has shown to help every animal have a loving family and a warm, snuggly place to call home," said Abbie Moore, executive director of Adopt-a-Pet.com. "With our combined efforts, we can bring together communities across the United States for one single mission - to find homes for loving pets who need to be adopted."
More information about the "Homes for Dogs Project" can be found at http://www.coldwellbanker.com/dogs.
Tuesday, February 16, 2016
Monday, February 15, 2016
Thursday, October 8, 2015
Dream Homes Turn Into "Scream" Homes with New Interactive Haunted House Feature on Realtor.com®
Buyers and sellers can now create the home of their dreams and worst nightmares on realtor.com®. Just in time for Halloween, realtor.com®, a leading provider of online real estate services operated by News Corp subsidiary Move, Inc. today announced the launch of "Build Your Own Haunted House."
 Consumers can build a spooky home complete with haunts and sounds and share it via email, Facebook or Twitter any time during the month of October. The haunted house option offers a menu of animated and customizable options such as lighting color to adorn the outside of the home as well as lawn features, including a customizable for-sale sign, tombstones, jack-o-lanterns and skeletons. Spooky homes also can be customized with flying features that include witches, ghosts, crows, or bats, and sounds from wailing ghosts, shrieking witches, thunder or wind to add even more fright.
Since no Halloween is complete without a creepy costume, users also have the option to place a headshot onto a zombie as part of their scary home scene. Once the house is complete, it comes alive with the sights and sounds of Halloween.
"At realtor.com, we want to make the home experience enjoyable, and what's more fun than having the opportunity to build your own haunted house and share it with friends and family," said Nate Johnson, chief marketing officer for realtor.com®. "This speaks to the brand experience we are trying to create at realtor.com."
Users are invited to "Share the Scare" with all their friends, an option which encourages them to show off their creepy creation by either sending a "Happy Halloween" email-o-gram with a personalized note or posting their haunted house to Twitter or Facebook.
Realtor.com®'s "Build Your Own Haunted House" will be available until midnight on Oct. 31.
About Move, Inc. and realtor.com®
Move, Inc. operates the realtor.com® website and mobile experiences, which provide buyers, sellers and renters of homes with the information, tools and professional expertise they need to discover and create their perfect home. News Corp [NASDAQ: NWS, NWSA; ASX: NWS, NWSLV] acquired Move in November 2014, and realtor.com® quickly established itself as the fastest growing online real estate service provider in the first half of 2015 as measured by comScore.
As the official website of the National Association of REALTORS®, consumers know they can look to realtor.com® for the most comprehensive and accurate information anytime, anywhere. With relationships with more than 800 multiple listing services (MLS), realtor.com® has more than 3 million for-sale listings, which account for more than 97 percent of all MLS-listed for-sale properties. More than 90 percent of the listings are updated every 15 minutes. Move's network of websites provides consumers a wealth of innovative tools, including Doorsteps®, Moving.com™, SeniorHousingNetSM and others. Move supports real estate professionals by providing many services to grow their businesses in an increasing digital, on-demand world, including ListHub™, the nation's leading listing syndicator and centralized intelligence platform for the real estate industry; TigerLead®; Top Producer® Systems; andFiveStreetSM and Reesio as well as many free services.
Tuesday, March 17, 2015
The Great Age Divide: How the young and the older buy real estate differently and what marketers need to know about it
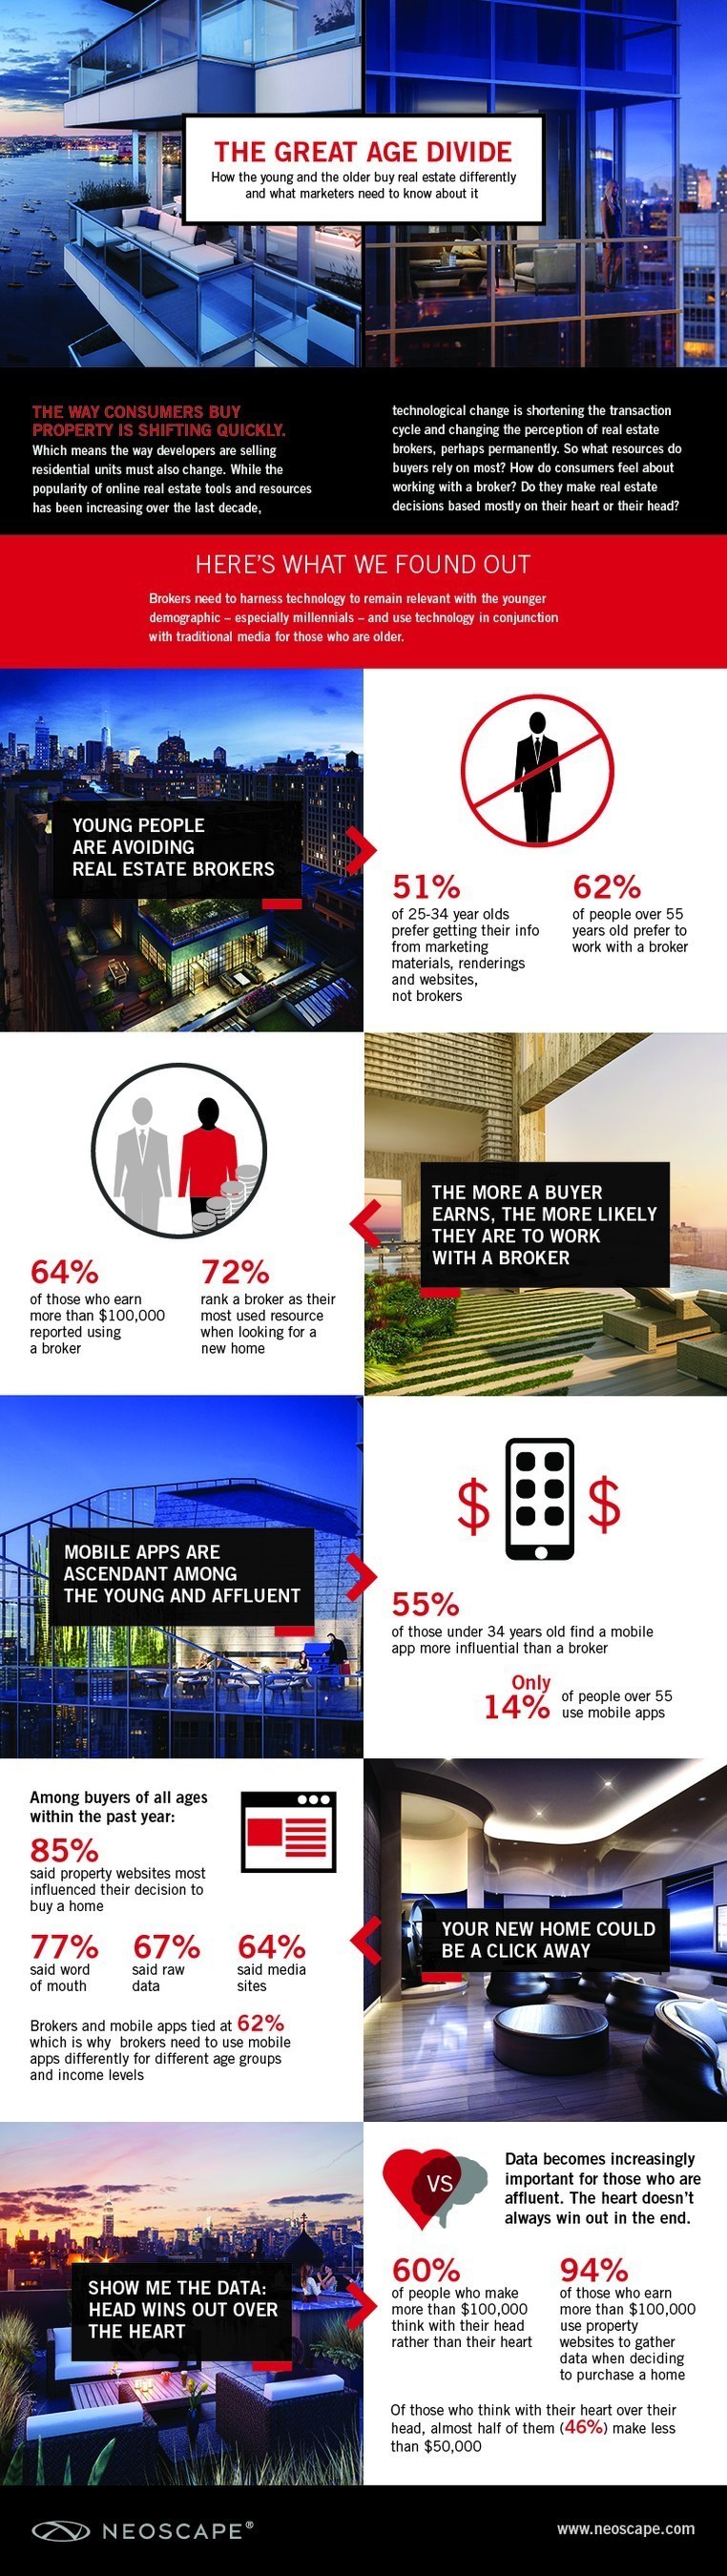 Fifty-one percent of 25-34 year olds say they don't want to work with a real estate broker when buying a home and prefer getting their house hunting information from marketing materials, renderings and websites, according to a survey by Neoscape, Inc. The sentiment is even stronger among 18-24 year olds, 81 percent of whom say they do not want to work with a broker, whereas only 38 percent of people over 55 years old did not want to work with a broker.
Mobile apps are also ascendant among the young and affluent:
- 55 percent of those under 34 years old find a mobile app more influential than a broker, whereas only 14 percent of people over 55 use mobile apps.
- Nearly a quarter of people who make more than $100,000 use mobile apps.
"While technology is changing how we shop for almost anything today, we were surprised by how quickly sentiment is changing about the traditional home buying process, and it's clear that the real estate industry needs to shift how it markets property – especially to first-time homebuyers, who are increasingly urban, savvier and more independent than ever. Brokers especially need to harness technology to remain relevant with the younger demographic," said Rodrigo Lopez, chief creative officer, Neoscape.
Meanwhile, when asked what most influenced their decision when they bought a home within the last year, 85 percent of buyers of all ages said property websites, followed by word of mouth at 77 percent. Brokers and mobile apps tied for influence at 62 percent, which is why brokers need to use mobile apps differently for different age groups and income levels.
Age is not the only factor that determines a buyer's willingness to rely on a broker. Income plays a big role, as well. The more a buyer earns, the more likely they are to work with a broker. Among the affluent who earn more than $100,000:
- 64 percent reported using a broker
- 72 percent rank a broker as their most used resource when looking for a new home
The survey also showed that data becomes increasingly important for those at the higher end of the income spectrum; the heart doesn't always win out in the end:
- 94 percent use property websites to gather data when deciding to purchase a new home
- 60 percent say they think with their head over their heart
- Of those who think with their heart over their head, almost half of them (46%) make less than $50,000
Survey Methodology:
Tuesday, March 10, 2015
NAR Generational Survey: Millennials Lead All Buyers, Most Likely to Use Real Estate Agent
Despite the economic and financial challenges young adults have braved since the recession, the millennial generation represented the largest share of recent buyers, according to the 2015 National Association of Realtors® Home Buyer and Seller Generational Trends study, which evaluates the generational differences of recent home buyers and sellers.
The survey additionally found that an overwhelming majority of buyers search for homes online and then purchase their home through a real estate agent, with millennials using agents the most.
For the second consecutive year, NAR's study found that the largest group of recent buyers was the millennial generation, those 34 and younger, who composed 32 percent of all buyers (31 percent in 2013). Generation X, ages 35-49, was closely behind with a 27 percent share. Millennial buyers represented more than double the amount of younger boomer (ages 50-59) and older boomer (60-68) buyers (at 31 percent). The Silent Generation (ages 69-89) made up 10 percent of buyers in the past year.
Lawrence Yun, NAR chief economist, says the survey highlights the untapped demand for homeownership that exists among young adults. "Over 80 percent of millennial and Gen X buyers consider their home purchase a good financial investment, and the desire to own a home of their own was the top reason given by millennials for their purchase," he said. "Fixed monthly payments and the long-term financial stability homeownership can provide are attractive to young adults despite them witnessing the housing downturn and subsequent slow recovery in the early years of their adulthood."
With millennials entering the peak buying period and expected to soon surpass boomers in total population, Yun believes the share of millennial purchases would be higher if not for the numerous obstacles that have slowed their journey to homeownership. "Many millennials have endured underemployment and subpar wage growth, and rising rents and repaying student debt have made it very difficult to save for a downpayment. For some, even forming households of their own has been a challenge."
According to the survey, 13 percent of all home purchases were by a multi-generational household, consisting of adult siblings, adult children, parents and/or grandparents.
The biggest reasons for a multi-generational purchase were cost savings (24 percent) and adult children moving back into the house (23 percent). Younger boomers represented the largest share of multi-generational buyers at 21 percent, with 37 percent of those saying the primary reason for their purchase was due to adult children moving back into their house.
"Even though the share of first-time buyers has fallen to its lowest level since 19871, young adults in general are more mobile than older households," adds Yun. "The return of first-time buyers to normal levels will eventually take place in upcoming years as those living with their parents are likely to form households of their own first as renters and then eventually as homeowners."
Characteristics of Buyers
The median age of millennial homebuyers was 29, their median income was $76,900 ($73,600 in 2013) and they typically bought a 1,720-square foot home costing $189,900 ($180,000 a year ago). The typical Gen X buyer was 41 years old, had a median income of$104,600 ($98,200 a year ago) and purchased a 1,890-square foot home costing $250,000 (same as last year).
Seventy-nine percent of all buyers considered their home purchase a good financial investment, with millennials (84 percent) and Gen X (82 percent) having the highest share, followed by younger and older boomers (both 77 percent), and the Silent Generation (72 percent).
Generation X buyers (68 percent) were the most likely to be married, younger boomers had the highest share of single female buyers (23 percent), and millennial buyers were more likely (compared to other generations) to be an unmarried couple (14 percent).
When asked about the primary reason for purchasing a home, a desire to own a home of their own was highest among millennials at 39 percent. Younger boomers were the most likely to buy because of a job-related relocation or move, and a change in a family situation – likely the birth of a child – was the highest (13 percent) among Gen X buyers. Older boomers (at 15 percent) were the most likely to buy because of retirement.
Searching for and Buying a Home
Regardless of their age, buyers used a wide variety of resources in searching for a home, with the Internet (88 percent) and real estate agents (87 percent) leading the way. Millennials were the most likely to use a real estate agent, mobile or tablet applications, and mobile or tablet search engines during their search; Gen X buyers were the most likely to use an open house.
Although the Internet was the top source of where millennials found the home they purchased (51 percent), they also used an agent to purchase their home at a higher share (90 percent) than all other generations.
NAR President Chris Polychron, executive broker with 1st Choice Realty in Hot Springs, Ark., says the survey results highlight the fact that while the Internet is widely used during the home search process, the local market knowledge and expertise a Realtor®provides is both valued and highly sought by buyers of all ages.
"Nothing can replace the real insights and guidance Realtors® deliver to help consumers navigate the complex buying and selling process," adds Polychron.
Although most purchases by all generations were in a suburban area, the share of millennials buying in an urban or central city area increased to 21 percent in the past year (19 percent a year ago), compared with only 12 percent of older boomers (unchanged from a year ago). Older boomers and the Silent Generation were more likely to buy in a rural area (18 percent each). Buyers' median distance from their previous residence was 12 miles, with older boomers moving the furthest at a median distance of 30 miles.
The majority of all buyers (79 percent) purchased a detached single-family home. Gen X buyers represented the largest share of single-family homebuyers (85 percent), and the Silent Generation was the most likely to purchase a townhouse or row house (10 percent). A combined 7 percent of millennial buyers bought an apartment, condo or duplex in a building with two or more units.
Among the biggest factors influencing neighborhood choice, millennials were most influenced by the quality of the neighborhood (75 percent) and convenience to jobs (74 percent). Convenience to schools was most desired by Gen X buyers and proximity to health facilities by the Silent Generation.
Millennials plan to stay in their home for 10 years, while the baby boom generation as a whole plans to stay for a median of 18 years.
Financing the Purchase
NAR's study found that 88 percent of all buyers in the past year financed their purchase. Millennials (97 percent) and Gen X (96 percent) were more likely to finance than older boomers (72 percent) and the Silent Generation (61 percent). The median downpayment ranged from 7 percent for millennial buyers to 20 percent for older boomers.
Younger buyers who financed their home purchase most often relied on savings for their downpayment, whereas older buyers were more likely to use proceeds from the sale of a primary residence. Younger buyers also were more likely to receive a gift from a relative or friend, typically their parents, cited by 25 percent of millennials and 15 percent of Gen X.
Twelve percent of all recent buyers had delayed their home purchase due to outstanding debt. Among the 22 percent of millennials who took longer to save for a downpayment, 54 percent cited student loan debt as the biggest obstacle – down slightly from 56 percent a year ago.
Younger buyers were more likely to finance their purchase with a low downpayment Federal Housing Administration-backed mortgage, whereas older buyers were more likely to obtain a mortgage through the Veterans Affairs loan program.
Characteristics of Sellers
Gen X homeowners represented the largest share of sellers in the past year (27 percent), followed by older boomers (23 percent) and younger boomers (20 percent). The older the seller, the longer he or she was in the home. Millennials had been in their previous home for a median of five years, while older boomers and the Silent Generation stayed for 13 years.
Younger sellers were more likely to need a larger home or move for job relocation. In comparison, older buyers wanted to be closer to family or friends, said their home was too large, or were moving due to retirement.
The survey additionally found that Gen X sellers were the most likely to have wanted to sell earlier but were stalled because their home had been worth less than their mortgage (23 percent compared to 16 percent for all sellers).
Sellers moved a median distance of 20 miles, with boomers and the Silent Generation moving further distances and downsizing to a smaller-sized home.
A combined 60 percent of responding sellers found a real estate agent through a referral by a friend, relative or neighbor, or used their agent from a previous transaction. Eighty-three percent are likely to use the agent again or recommend to others.
While all sellers wanted help in marketing their home to potential buyers, younger sellers were more likely to want their agent to help with pricing the home competitively or selling within a specific timeframe.
NAR mailed a 127-question survey in July 2014 using a random sample weighted to be representative of sales on a geographic basis. A total of 6,572 responses were received from primary residence buyers. After accounting for undeliverable questionnaires, the survey had an adjusted response rate of 9.4 percent. The recent homebuyers had to have purchased a home between July of 2013 and June of 2014. Because of rounding and omissions for space, percentage distributions for some findings may not add up to 100 percent.
All information is characteristic of the 12-month period ending in June 2014 with the exception of income data, which are for 2013.
The 2015 NAR Home Buyer and Seller Generational Trends study is posted at: http://www.realtor.org/reports/home-buyer-and-seller-generational-trends.
The National Association of Realtors®, "The Voice for Real Estate," is America's largest trade association, representing 1 million members involved in all aspects of the residential and commercial real estate industries.
1NAR's 2014 Profile of Home Buyers and Sellers found the share of sales to first-time buyers dropped 5 percentage points from 2013 to 33 percent, representing the lowest share since 1987 (30 percent).
Friday, August 22, 2014
Only a Dozen Large Metro Housing Markets Feature Both Affordable For-Sale Housing and Affordable Rental Housing
Renting is currently more expensive than ever in many areas, according to Zillow, making it difficult for renters to save for a down payment on a home
- Homes remain more affordable to buy in 94 of country's 100 largest metros compared to historic averages. But renting is more expensive than ever in 88 of the country's 100 largest markets.
- The Zillow Home Value Index rose to $174,800 in July, up 0.2 percent from June 2014 and 6.5 percent from June 2013.
- After three months of flat or negative monthly growth, national rents rose 0.6 percent in July from June, to a Zillow Rent Index of $1,318.
SEATTLE -- Of the nation's 100 largest metro areas, only a dozen are currently more affordablei than they historically have been for both renters and homeowners, as widespread growth in housing costs continues to outpace wage growth. Nationally, U.S. home values rose 6.5 percent year-over-year in July, according to the July Zillow® Real Estate Market Reportsii, while national rents rose 2.8 percent over the same period.
Rental affordability is currently much worse than mortgage affordability, largely because rents didn't experience the huge drop seen in home values during the recession, and instead have just kept climbing upward. Nationally, renters signing a lease at the end of the second quarter paid 29.5 percent of their income to rent, compared to 24.9 percent in the pre-bubble period. In 88 of the nation's largest metro areas, renters should currently expect to pay a larger share of their income toward rent than they would have historically.
Thanks mostly to low mortgage interest rates, affordability of for-sale homes looks much better. U.S. home buyers at the end of the second quarter could expect to pay 15.3 percent of their incomes to a mortgage on the typical home, far less than the 22.1 percent share homeowners devoted to mortgages in the pre-bubble days. As of June, home buyers in just six of the country's 100 largest metro markets analyzed by Zillow were paying a larger portion of their incomes today than historically in order to buy their area's median-priced home.
But mortgage rates are expected to rise in the coming year. When mortgage rates hit 5 percent, still very low by historical standards, the number of unaffordable metros for homeowners among the top 100 will more than double, to 13. At 6 percent mortgage interest rates, the number of unaffordable metros will almost double again, to 24.
"The affordability of for-sale homes remains strong, which is encouraging for those buyers that can save for a down payment and capitalize on low mortgage interest rates. But the health of the for-sale market is directly tied to the rental market, where affordability is really suffering" said Zillow Chief Economist Dr. Stan Humphries. "As rents keep rising, along with interest rates and home values, saving for a down payment and attaining homeownership becomes that much more difficult for millions of current renters, particularly millennial renters already saddled with uncertain job prospects and enormous student debt. In order to combat this phenomenon, wages need to grow more quickly than they are, particularly for renters, and growth in home values will need to slow."
The median annual income nationwide was $53,216 as of the end of the second quarteriii. But according to the Census Bureau, homeowners and renters make drastically different salaries – homeowners make $65,514 per year, while the typical renter in the U.S. makes just $31,888iv.
In July, median U.S. home values rose 0.2 percent from June, to a Zillow Home Value Indexv of $174,800, the slowest monthly pace of appreciation since February 2012. Looking ahead, for the 12-month period from July 2014 to July 2015, national home values are expected to rise another 2.7 percent to approximately $179,489, according to the Zillow Home Value Forecastvi.
Median U.S. rents rose 0.6 percent in July from June, to a Zillow Rent Indexvii of $1,318. The monthly spike in rents follows three straight months of flat or falling rents.
Subscribe to:
Posts (Atom)